
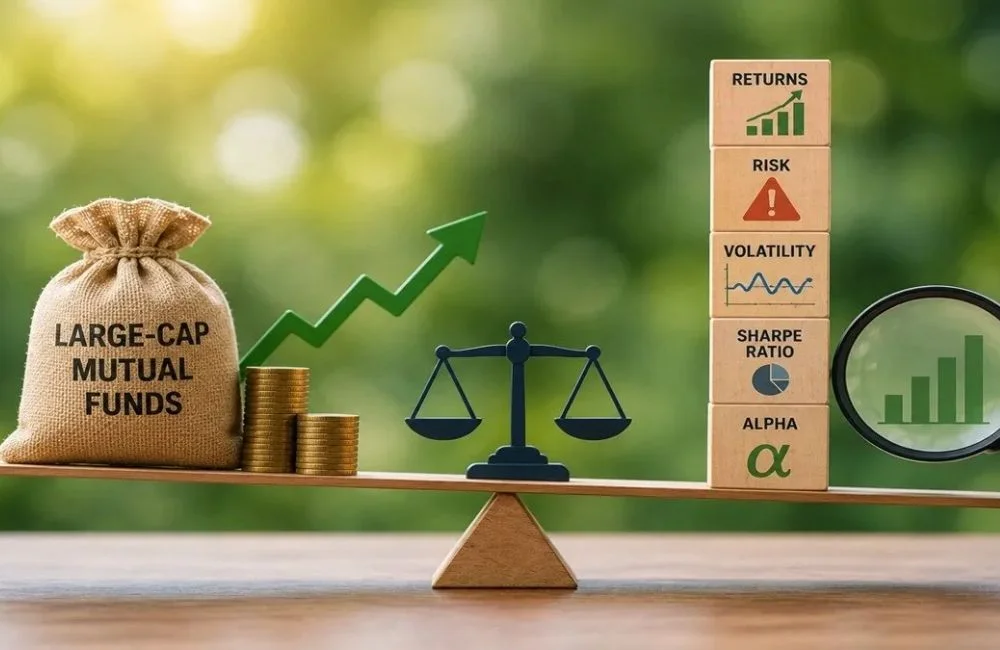
Large Cap Mutual Funds predominantly invest in shares of large companies. SEBI rules say large cap funds need to hold at least 80% of assets in large cap stocks. SEBI defines large cap firms as those ranked 1 to 100 by full market value. This funding can help to achieve long-term goals. But their values rise and fall with the stock market.
There is no single amount that works for everyone. It is determined by your income, bills, debt, goals, time and comfort level with risk. A simple plan can help you find an amount that fits your own cash flow.
Step 1: Keep Cash for Your Immediate Needs
Begin with an emergency fund. This should include major expenses like rent, food, bills and loan dues.
Do not invest money needed in the near term in equity mutual funds. The money may fall in share price when it is due. Also look at health and life cover where necessary. It can help prevent a short-term bill from derailing a longer-term plan.
Step 2: Define a Clear Goal
Write down three things. The goal. The sum. The date. The fee for a course next year is not a home fund payable in eight years.
Large Cap Mutual Funds are Equity Schemes. They may be suitable for goals that allow for the market to experience both ups and downs. A short-term goal may require cash, a bank deposit or other asset with a stable value.
For each goal, ask yourself:
- What total are we going for?
- When will the money be spent?
- Is the date changeable?
- What is the plan’s tolerance for loss over time?
Step 3: Work Out Your Monthly Free Cash
Use the formula: Monthly Income – Key Bills – Debt Dues – Cover Costs – Near Term Saving = Free Cash. Think about expenses that aren’t monthly. These can be home repairs, school fees, trips or tax payments.
Suppose a person earns ₹80,000 in a month. Fixed dues and key costs are ₹ 55,000. An amount of ₹5,000 is kept for short-term needs. The free cash is Rs. 20,000.
Step 4: Equity Share Setting
Determine how much free cash can be put into equity. Use risk comfort and goal date as a basis. Don’t use past returns as your sole guide.
The person should use an equity sum, which he is able to hold during a phase when a sharp fall occurs, so that he can stop a plan. See the Riskometer scheme. Fund houses have to show it to SEBI . The scale is from low to very high risk.
Also, check to see if the goal already has exposure to stock through shares, an index fund, a pension plan or other mutual funds. Add all equity into one pool.
Step 5: Define Large Cap Share
Once you are sure about the equity amount, opt for the Large Cap Mutual Funds section. Apply this formula: Free cash X large cap share X equity share = large cap total
Take the above example. Free Cash is 20,000. Assume 60% is for equity, that is Rs. 12,000. If this equity sum is halved and invested in a large cap fund, the monthly sum would be ₹6,000.
This is just an example, not a hard and fast rule. Another plan might use a different mix depending on its goal, cash flow and risk level.
Step 6: Verify the Scheme
Read the scheme paper and the factsheet. Check its objective, index, portfolio, fee, exit load, Riskometer, fund process. Past performance is not indicative of future results.
Avoid buying large cap funds that hold identical key stocks. This could lead to overlap. It can make a plan look broad even if the same firms are driving its value.
Step 7: Choose a Payment Method
The sum can be tied to regular income through a monthly plan. A lump sum can also accommodate cash already allocated to a long goal. The choice should correspond to the source of funding. It should not be a guess as to what the next market move will be.
Step 8: Check the Total
Review the plan annually. Come back to it after a job change, pay rise, loan, birth or new goal. Change the total when the plan changes. Don’t overtrade every market move.
See if the large cap share has drifted off the set mix. Rebalance only as per plan and tax impact.
Conclusion
The aim is to have the right amount in Large Cap Mutual Funds. Keep some cash for emergencies. Calculate free cash . Calculate the equity share . Then calculate the large cap share . Apply the formula for a clean sum. Examine risk, fees and fund overlap. This keeps the choice a question of need, not mood or market noise. If tax, debt or goals make it hard to assess the plan, get help from a SEBI-registered adviser.